
October 23, 2026
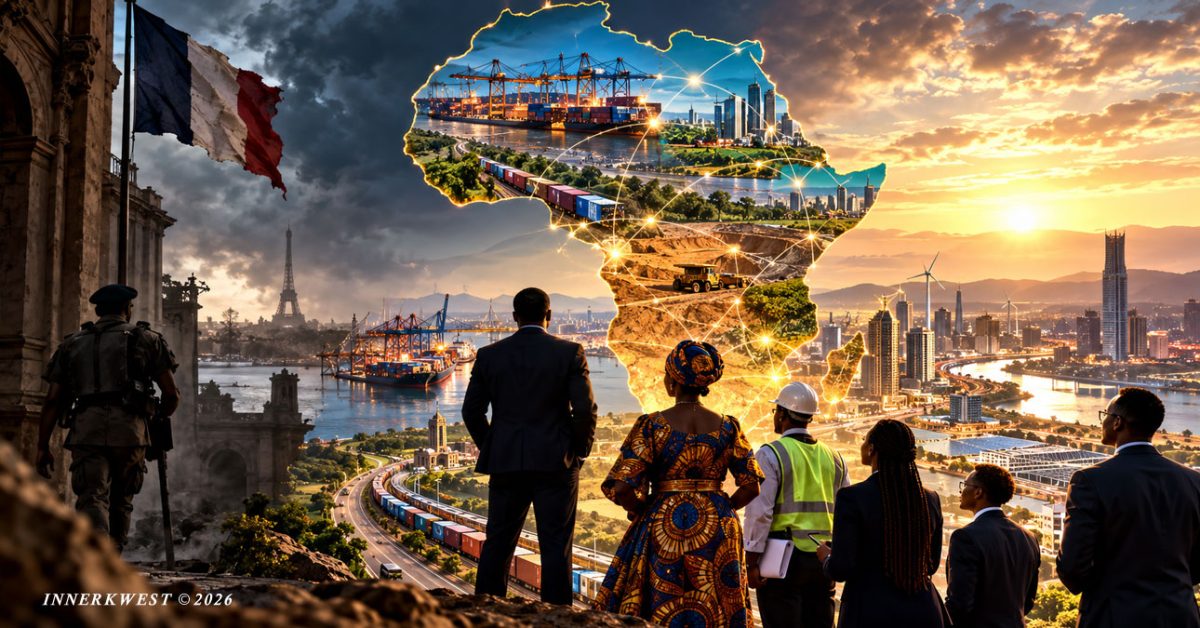
Political independence removed flags and administrations. Economic independence has proved more complicated. Across Africa, institutions are emerging around money, trade, energy, food, minerals and security that raise a different question: what happens when relationships inherited from dependency are no longer necessary?
By the InnerKwest Editorial Desk
There are moments when an international order changes loudly. Governments fall, armies cross borders, treaties are abandoned, flags come down and new ones rise above government buildings while crowds gather beneath them. History recognizes these moments easily because they photograph well.
Other transformations arrive through payment systems, central banks, warehouses, transmission lines, credit assessments, ports, refineries, rail corridors and decisions taken inside conference rooms where almost no one outside the institution is paying attention.
Africa may be entering one of those quieter moments.
Not because the continent has suddenly achieved economic independence, nor because fifty-four sovereign governments have discovered a common economic philosophy. The relationships connecting African economies to Europe, the United States, China, the Gulf states and the wider international financial system are not disappearing. They remain substantial and, in many cases, necessary.
But necessity is not a permanent condition.
For much of the period following African independence, sovereignty existed beside structures that independence did not immediately dismantle. Political administrations changed while trading relationships endured. New governments inherited currencies, commercial networks, transportation systems and financial institutions designed during another period and often for another purpose. Raw materials continued traveling outward while manufactured goods returned. Capital frequently moved through institutions headquartered elsewhere. Security relationships survived the lowering of colonial flags. Even the international judgment of whether an African government represented a good financial risk was largely produced beyond the continent.
Political independence had arrived. Economic geography proved more stubborn.
What is beginning to move now is not necessarily Africa’s relationship with the outside world, but the number of alternatives available within Africa itself.
The African Union formally launched the Africa Credit Rating Agency in Mauritius this year after years of institutional preparation. AfCRA is structured as a private-sector-driven institution in which governments cannot own shares. Its purpose is not to prevent Moody’s, S&P or Fitch from evaluating African sovereigns and companies, but to establish an African institution capable of producing assessments through methodologies informed by African data and economic conditions.
Its arrival touches a question larger than ratings.
Credit assessments influence what governments pay to borrow, which securities institutional investors can hold, how risk is perceived and how much development can be financed before a road, hospital, electrical plant or university is ever built. UNDP research has estimated that subjectivities and deficiencies in the existing sovereign-rating system have cost African countries roughly $75 billion through excessive interest costs and foregone lending. Its more recent work identifies foreign-currency bias, insufficient consideration of informal economies and asymmetric treatment of African risk among the structural problems affecting assessments.
An African rating agency will not correct those problems merely by existing. AfCRA will have to establish the credibility of its methodology, governance and analytical independence through performance. An African institution can be wrong. It can become compromised. It can reproduce the very weaknesses it was established to challenge.
But there is another assumption worth examining.
Who is the investor whose confidence Africa is supposed to earn?
For decades, much of the discussion surrounding African investment has been written as though capital were standing outside the continent looking inward, deciding whether Africa had made itself sufficiently attractive. That capital remains important and will remain welcome where governments consider its terms advantageous. But it is no longer sufficient to speak about African development as though the investor necessarily lives somewhere else.
The African Development Bank now estimates that Africa’s financial ecosystem contains more than $4 trillion in domestic capital spread across commercial banks, pension and insurance funds, foreign-exchange reserves, development banks, sovereign wealth funds and other pools. Much of it is fragmented, invested conservatively or held in assets that do little to finance long-term African productive capacity. The Bank estimates that less than 2.7 percent of institutional balance-sheet assets are presently deployed toward domestic long-term productive investment.
That is a weakness.
It is also a possibility.
If African capital begins financing more African infrastructure, African manufacturing and African enterprises across national borders, the familiar relationship between Africa and the outside investor begins to change. Foreign capital does not disappear. Its monopoly over the imagination does.
The investor across the table may increasingly be African.
So may the bank.
So may the pension fund.
So may the market.
The Architecture Beneath Independence
Money has always revealed more about sovereignty than flags.
The CFA franc remains one of the most visible inheritances of France’s relationship with portions of West and Central Africa, although the contemporary arrangement resists easy slogans. West African reforms have already removed French representatives from BCEAO decision-making bodies and ended the requirement that foreign reserves be centralized in an operations account at the French Treasury, while retaining the fixed parity with the euro and the French guarantee of convertibility. Central Africa’s monetary arrangements remain different.
The old structure has therefore neither remained untouched nor simply disappeared.
It is being negotiated.
That may become characteristic of this period. Institutional independence is unlikely to arrive across Africa as a single declaration. It may develop unevenly as alternatives accumulate until arrangements once regarded as indispensable become one possibility among several.
The Pan-African Payment and Settlement System offers an early example. PAPSS allows participating institutions to facilitate cross-border African payments while reducing the need for transactions between African countries to travel unnecessarily through external currencies and correspondent banking relationships. Its network has continued expanding across the continent.
The underlying question is almost embarrassingly simple. Why should a business in one African country purchasing from a business in another necessarily require a financial journey through currencies and institutions outside Africa before the transaction can be settled?
For decades the answer was largely structural: because that was where the financial architecture existed.
Now another architecture is being built.
The African Continental Free Trade Area extends the same question from payments to markets. Africa’s internal commerce remains far below its potential, constrained by inadequate transport corridors, border delays, incompatible regulations, financing shortages, conflict and infrastructure that in many places was designed historically to move commodities from the interior toward ports rather than between African economies.
UNECA simulations estimate that full implementation of AfCFTA could make intra-African trade approximately 45 percent higher by 2045 than under a scenario without the agreement, representing roughly $276 billion in additional commerce.
The number is useful.
It is not destiny.
Economic models necessarily construct futures from assumptions. They estimate what may happen if certain variables move in anticipated ways while others remain within defined ranges. The $276 billion figure should therefore be understood for what it is: one institutional estimate of what integration could produce under a particular set of conditions, not an outer boundary against which African ambition should be measured.
What happens if the conditions themselves change faster than the model anticipates?
What happens if African institutional capital begins financing more African production; if payment friction falls; if energy becomes more reliable; if minerals are increasingly processed before export; if transportation corridors connect African producers more efficiently to African consumers; if capital markets deepen; if informal trade becomes formal enough to finance and measure; if a continent of adjacent economies gradually becomes a more interconnected marketplace?
UNECA itself acknowledges that AfCFTA’s ultimate performance will depend not merely upon tariff agreements but upon industrial capacity, infrastructure and the ability of the African private sector to use the market being created.
The future therefore remains open.
This matters because projections produced by respected international institutions can quietly acquire a cultural authority greater than the models themselves warrant. Numbers begin as scenarios and eventually get repeated as expectations. Expectations become narratives. Narratives influence investors, governments and sometimes Africans themselves.
Africa has spent enough of its history living inside projections produced elsewhere.
Even African institutions should not be allowed to turn projections into ceilings.
The more interesting development is that a market is being constructed beneath the numbers: payment infrastructure, trade rules, financing institutions and, eventually, deeper monetary coordination. The African Union continues work toward an African Monetary Institute intended to support greater monetary cooperation and potentially precede a future African Central Bank. Neither a continental central bank nor a single African currency is imminent. The work remains institutional preparation.
Unfinished architecture should not be mistaken for a completed building.
Neither should it be mistaken for nothing.
When the Soldiers Leave
Economic arrangements are not changing alone.
France’s military presence across parts of Africa has contracted with remarkable speed. French troops have left Mali, Burkina Faso and Niger. Chad terminated its defense cooperation agreement. Senegal insisted upon the withdrawal of French forces from its territory, and France returned its remaining bases there in 2025.
The significance should not be exaggerated.
Removing a foreign military base does not create an effective national army. Ending one security relationship does not automatically produce another capable of controlling borders, confronting insurgencies or protecting infrastructure. The Sahel itself demonstrates how dangerous the distance between political sovereignty and security capacity can become.
Yet speed matters.
Relationships once treated almost as fixtures have changed within years.
That challenges an assumption surrounding African economic sovereignty: that meaningful institutional separation must necessarily unfold over several generations.
Productive capacity may indeed require decades. Industrial ecosystems cannot be legislated into existence. Electrical grids take time. Engineers must be educated. Capital must accumulate. Roads, ports and railways must be built and maintained. Financial institutions acquire credibility through performance rather than declarations.
Political decisions can move much faster.
And once credible alternatives appear, they can move faster still.
A government can ask foreign soldiers to leave tomorrow. Building the institutions that make their return unnecessary is harder.
The distance between those two events may tell us more about African sovereignty than either event alone.
France, Looking Inward
Across the Mediterranean, France is confronting a different question of institutional capacity.
Its present civil unrest should not be casually attributed to Africa. France’s fiscal difficulties have substantial domestic origins: public debt, pension obligations, weak growth, taxation, political fragmentation, demographic pressures and long-running disagreement over what the French state promises its citizens and how those promises should be financed.
Africa did not create those problems.
History does not require one event to cause another before their convergence becomes important.
France entered this period under severe social strain. Protest over educational conditions, living costs and public services has unfolded alongside pressure on household purchasing power and growing difficulty reconciling public expectations with the state’s fiscal room. French government finances increasingly carry the weight of obligations accumulated over decades.
This is not evidence that France is collapsing.
It is evidence that choices are becoming harder.
That distinction matters. Wealthy countries can endure enormous debt. Infrastructure can deteriorate unevenly without becoming dysfunctional. Political unrest can subside. Governments can restructure expenditures and recover growth.
But a state that must devote increasing resources to servicing existing obligations has less freedom to answer every new demand. When citizens expect the state to provide more at precisely the moment the state finds it increasingly difficult to do so, fiscal arithmetic becomes political reality.
This is where Africa re-enters the story, not as culprit but as changing counterpart.
France is being required to manage growing domestic constraints during the same historical period in which African governments are renegotiating military relationships, reconsidering inherited monetary structures, developing alternative financial institutions and seeking to retain more value from their own economies.
No serious analysis should pretend that the departure of a French military contingent from Senegal explains a French budget deficit.
But serious analysis should be equally reluctant to assume that the gradual disappearance or renegotiation of advantages accumulated through decades of privileged political, military and commercial relationships carries no consequence at all.
The effects may be difficult to isolate because history rarely supplies economists with clean laboratories. One agreement changes here, a procurement relationship changes elsewhere, a military presence disappears, an African company acquires a larger share of a market, a mineral-processing plant opens closer to the mine, another government renegotiates a contract. Individually, none need alter the trajectory of a European economy.
Accumulation is different.
The question is not whether Africa created France’s predicament.
It is whether the erosion of inherited advantages may make an already difficult adjustment more difficult.
The Value That Leaves
Africa’s resource wealth has never guaranteed African wealth.
That distinction may be among the most important economic lessons of the postcolonial period.
A mineral in the ground is not industrial capacity. Oil beneath a coastline is not a refinery. Arable land is not food security, sunlight is not an electrical grid, and a young population is not automatically a skilled workforce.
Exports are not the same thing as retained value.
The African Union’s Green Minerals Strategy now explicitly calls for movement beyond the export of raw critical minerals toward local beneficiation, processing, manufacturing and integrated African value chains. The economic reason is visible wherever a resource leaves the continent in one form and returns carrying considerably more value in another.
There lies the older economic order in miniature.
The world needs the mineral. Africa possesses it. Yet much of the higher-value work can occur somewhere else: financing, refining, component manufacturing, technological development, branding and final production. The ore travels outward while much of the margin settles elsewhere.
Changing that equation is considerably more difficult than changing the destination of an export ship. It requires electricity, industrial finance, technical education, transportation, water, processing facilities, predictable regulation and markets large enough to support production.
It also requires investors.
But here again the language matters.
The investor need not always arrive at an African airport.
Africa’s own pension funds, banks, insurers, sovereign funds, enterprises and diaspora possess capital. The African Development Bank’s estimate of more than $4 trillion in domestic financial assets does not mean $4 trillion is immediately available for industrial development; much of it serves other obligations, is fragmented across jurisdictions or must remain invested according to prudential rules.
The institutional challenge is not to pretend those constraints away. It is to ask why so little African capital presently finds its way into long-term African productive investment and what would have to change for more of it to do so.
This produces a different conception of self-reliance from the one usually imagined.
China’s development offers lessons in productive capacity, industrial policy and the bargaining power that follows economic strength, but Africa is not China. China operates as a sovereign state under one central government and one national monetary framework. Africa consists of dozens of sovereign governments with different currencies, political systems, legal structures, resources and development priorities.
Africa’s path therefore cannot simply be Chinese self-reliance reproduced on another geography.
It may become something else.
Continental interdependence can become an instrument of national independence.
A Ghanaian institution investing in Kenyan infrastructure is not evidence of Kenyan dependency upon an external power. A Nigerian manufacturer selling into Côte d’Ivoire, a South African pension fund financing infrastructure elsewhere on the continent, a Kenyan bank supporting regional enterprise or a Moroccan company building productive capacity farther south creates relationships of dependence, certainly—but they are relationships inside an expanding continental economic system whose participants can themselves accumulate capital, expertise and bargaining power.
The objective need not be independence from one another.
It may be enough to become less dependent upon everyone else.
Feed, Fuel, Defend and Finance
Strategic autonomy eventually encounters ordinary things.
Food is one of them.
Africa possesses immense agricultural potential while remaining heavily exposed to imported food, climate shocks, conflict, inadequate irrigation, weak logistics and insufficient storage. A continent that cannot reliably feed its population remains vulnerable to decisions and disruptions occurring far beyond its borders.
Energy follows closely behind. Industrial sovereignty without reliable electricity remains largely rhetorical because power is what turns mineral wealth into processing, agricultural production into refrigerated supply chains and young populations into technologically productive workforces. Electricity powers irrigation pumps, factories, hospitals, rail systems, schools and data centers. It is difficult to identify a serious development ambition that does not eventually arrive at the electrical grid.
Security protects whatever those systems create. No state possesses meaningful economic sovereignty if its ports, mines, pipelines, farms, transmission networks and population centers cannot be protected. Yet security independence need not mean isolation. African governments will continue purchasing equipment abroad, forming alliances and cooperating with foreign partners just as governments elsewhere do. The difference lies in whether a partnership is chosen because its terms are advantageous or accepted because no workable alternative exists.
And eventually each of these questions reaches finance.
Someone must pay for the irrigation, transmission lines, refineries, universities, ports, defense systems, factories and railways. Natural resources can contribute. Taxes can contribute. Foreign investors can contribute. So can domestic banks, pension funds, sovereign funds, capital markets, diaspora investment and African investors operating across borders.
The continent’s problem is therefore not simply an absence of money. The African Development Bank now frames part of the problem as one of financial architecture: capital exists, but it is fragmented, conservatively deployed and insufficiently directed toward productive investment.
That reframes sovereignty itself.
Food security, energy, industrialization, finance and defense are not independent ambitions assembled beneath convenient headings. They interact. Reliable energy makes processing possible; processing creates enterprises and employment; productive enterprises deepen the tax base; functioning capital markets and financial institutions can redirect savings toward infrastructure; infrastructure expands agricultural and industrial markets; security protects the system long enough for capital to remain invested.
Capacity begins to compound.
So does negotiating power.
Who Gets to Price Africa?
There is another form of infrastructure that cannot be photographed from a highway.
Information.
Countries are governed partly by how the world understands them. Credit assessments, economic databases, research institutions, financial publications, investment reports and increasingly the information ingested by artificial-intelligence systems all contribute to an economy of perception.
Eventually perception acquires a price.
African governments have experienced this directly in sovereign debt markets. UNDP’s work describes an “Africa premium” in borrowing costs and identifies structural limitations in existing rating methodologies. In discussions around credit-rating reform, African governments have been described as paying substantially more to borrow than comparable countries elsewhere, reducing the money available for infrastructure, education, health and productive investment.
This is not evidence that every unfavorable African credit rating is unfair.
African governments have defaulted. Fiscal management has sometimes been poor. Political instability, currency weakness, debt accumulation and governance failures are real risks, and African sovereignty cannot mean demanding that investors ignore them.
Equal scrutiny requires something harder.
Comparable risks should be evaluated comparably.
That principle becomes particularly important when the cost of disagreement is measured in billions of dollars of interest.
AfCRA therefore matters for reasons beyond whether London or New York eventually approves of its ratings. If African pension funds, banks, insurers, sovereign funds and enterprises increasingly invest across the continent, African financial institutions will themselves require sophisticated assessments of African risk.
The audience for African financial intelligence can increasingly be African.
This does not eliminate the international rating agencies. It changes the informational environment around them.
An institution does not acquire authority by producing the answer its government prefers. Nor does an African rating agency serve Africa by systematically rating African governments more generously. That would simply replace one credibility problem with another.
Authority arrives when an institution produces analysis serious enough that markets cannot comfortably ignore it.
The larger question is therefore no longer simply whether Africa can persuade external investors that it deserves cheaper capital.
It is whether Africa can develop a financial architecture in which someone else’s perception of African risk no longer possesses the same power to determine the price of African development.
The Old Order Does Not Have to Disappear
Established institutions rarely surrender advantage because history has decided their time has passed.
They adapt. They compete, renegotiate, invest in emerging institutions, defend existing arrangements and search for new ones.
None of this automatically constitutes conspiracy.
It is what institutions do.
African institutions will do the same.
The useful investigative question is not whether Western governments secretly intend to prevent African economic independence. Western governments do not possess identical interests, and neither do their corporations, investors or populations.
The more revealing questions concern incentives. Who benefits financially when a particular dependency continues? Who benefits when it ends? Who controls access to essential infrastructure? Who writes the standards an emerging institution must satisfy? Are those standards applied consistently? Can influence survive through financing and governance even after formal political control has disappeared?
There is no requirement that the answers always implicate someone outside Africa.
African elites can preserve dependencies that benefit them. Governments can misuse institutions established in the name of sovereignty. Domestic monopolies can become as extractive as foreign ones. Regional integration can produce winners and losers, and a large African company can dominate a smaller African market just as an external multinational can.
African agency includes the capacity to make mistakes.
That is not an argument against sovereignty.
It is one of sovereignty’s conditions.
The World After Necessity
There is a temptation whenever Africa discusses self-reliance to imagine withdrawal from the international system.
That is a mistake.
China did not become influential by refusing to trade, and Japan did not accumulate financial power by disconnecting itself from international markets. Neither provides a political or economic template that Africa can simply reproduce.
The relevant lesson is narrower.
Capability changes bargaining power.
A country capable of manufacturing what others need negotiates differently. A country with reliable electricity negotiates differently. A country possessing capital and multiple markets for its products negotiates differently. None becomes independent of the world.
It acquires choices within it.
Africa’s internal scale makes this possibility particularly consequential. More than 1.5 billion people live across the continent. Those governments will disagree. Some will maintain close relationships with former colonial powers; others will deepen partnerships with China, the United States, India, Russia, Turkey, Japan, Brazil or the Gulf. Many will deal with several simultaneously.
The future does not require replacing dependence upon Europe with dependence upon Beijing, Moscow, Washington or anyone else.
Nor does it require every African state to become economically self-contained.
A more plausible future is one in which capital, goods, energy, expertise and investment circulate more freely within Africa while external relationships remain numerous enough that no single one becomes indispensable. In that environment, the accumulation of choices matters more than the identity of any preferred partner.
That is where intra-African investment becomes as important as intra-African trade.
The continental market cannot reach its potential if African countries merely sell more goods to one another while continuing to look almost exclusively outside the continent for the capital required to produce them. Trade integration and financial integration eventually meet. UNECA itself acknowledges that AfCFTA’s expected benefits depend partly upon higher levels of intra-African investment and the capacity of African private enterprise to use the market being created.
The question is no longer simply how much foreign investment Africa can attract.
It is how much African investment Africa can retain, mobilize and circulate.
That may prove more disruptive to the inherited order than any speech about economic independence.
The Speed of Becoming Unnecessary
For generations, the central question surrounding African independence was whether the continent could free itself from structures inherited from colonialism.
Perhaps the question is becoming too narrow.
French soldiers have left countries where their presence once appeared permanent. A continental payment system is creating settlement routes that did not previously exist. An African credit-rating institution has emerged where there was once primarily an argument for one. Governments are negotiating trade under a continental framework while financial institutions are beginning to confront the extraordinary fact that trillions of dollars in African capital coexist with an enormous African development-financing deficit.
None of this constitutes economic independence.
Some projects will fail. Some institutions will become bureaucratic. Governments will make poor decisions. Foreign partnerships will remain indispensable in important sectors. New dependencies may replace old ones if African states mistake a change of partner for a change of structure.
History offers no guarantee that institutions built in the name of sovereignty will produce it.
But something has changed nevertheless.
The conversation is moving, however unevenly, from whether alternatives should exist toward the harder work of making them function.
Perhaps that is where the international consequences will eventually become visible—not when Africa announces its separation from an old economic order, but when separation itself ceases to be the objective because the underlying dependency has begun to lose its necessity.
The payment can increasingly be settled through African infrastructure. Capital that once looked automatically outward can begin looking across the continent. A mineral can acquire more value before leaving the country that produced it. Electricity can power the factory that once existed only overseas. An African investor can finance an African enterprise serving African markets. A credit judgment made abroad can encounter another institution possessing its own data, methodology and reputation.
None of this requires France to disappear from Africa.
Europe need not disappear.
Neither must China, America, India, Japan, Brazil, Russia or the Gulf states.
Africa does not need isolation from them.
It needs enough capacity to tell any of them no—and enough confidence to say yes when the terms serve African interests.
Political independence gave African governments the authority to make that choice. Institutional independence determines how often the choice is real.
The next chapter may therefore be measured less by which foreign power is gaining Africa and which is losing it. Africa is not something to be gained.
The more consequential measure will be how many things once obtainable only through external dependency can increasingly be produced, financed, secured, evaluated, exchanged and negotiated within a continental system in which Africans themselves hold more of the capital, build more of the institutions and determine more of the terms.
When that capacity becomes sufficiently established, the question confronting the international order changes.
It is no longer whether Africa can survive without the arrangements it inherited.
It is whether those arrangements can survive once Africa no longer needs them.
At InnerKwest.com, we are committed to delivering impactful journalism, deep insights, and fearless social commentary. Your cryptocurrency contributions help us execute with excellence, ensuring we remain independent and continue to amplify voices that matter.
To help sustain our work and editorial independence, we would appreciate your support of any amount of the tokens listed below. Support independent journalism:
BTC: 3NM7AAdxxaJ7jUhZ2nyfgcheWkrquvCzRm
SOL: HxeMhsyDvdv9dqEoBPpFtR46iVfbjrAicBDDjtEvJp7n
ETH: 0x3ab8bdce82439a73ca808a160ef94623275b5c0a
XRP: rLHzPsX6oXkzU2qL12kHCH8G8cnZv1rBJh TAG – 1068637374
SUI – 0xb21b61330caaa90dedc68b866c48abbf5c61b84644c45beea6a424b54f162d0c
and through our Support Page.
InnerKwest maintains a revelatory and redemptive discipline, relentless in advancing parity across every category of the human experience.
© 2026 InnerKwest®. All Rights Reserved | Haki zote zimehifadhiwa | 版权所有. InnerKwest® is a registered trademark of Inputit™ Platforms Inc. Global. No part of this publication may be reproduced, distributed, or transmitted in any form or by any means without prior written permission. Unauthorized use is strictly prohibited. Thank you for standing with us in pursuit of truth and progress!